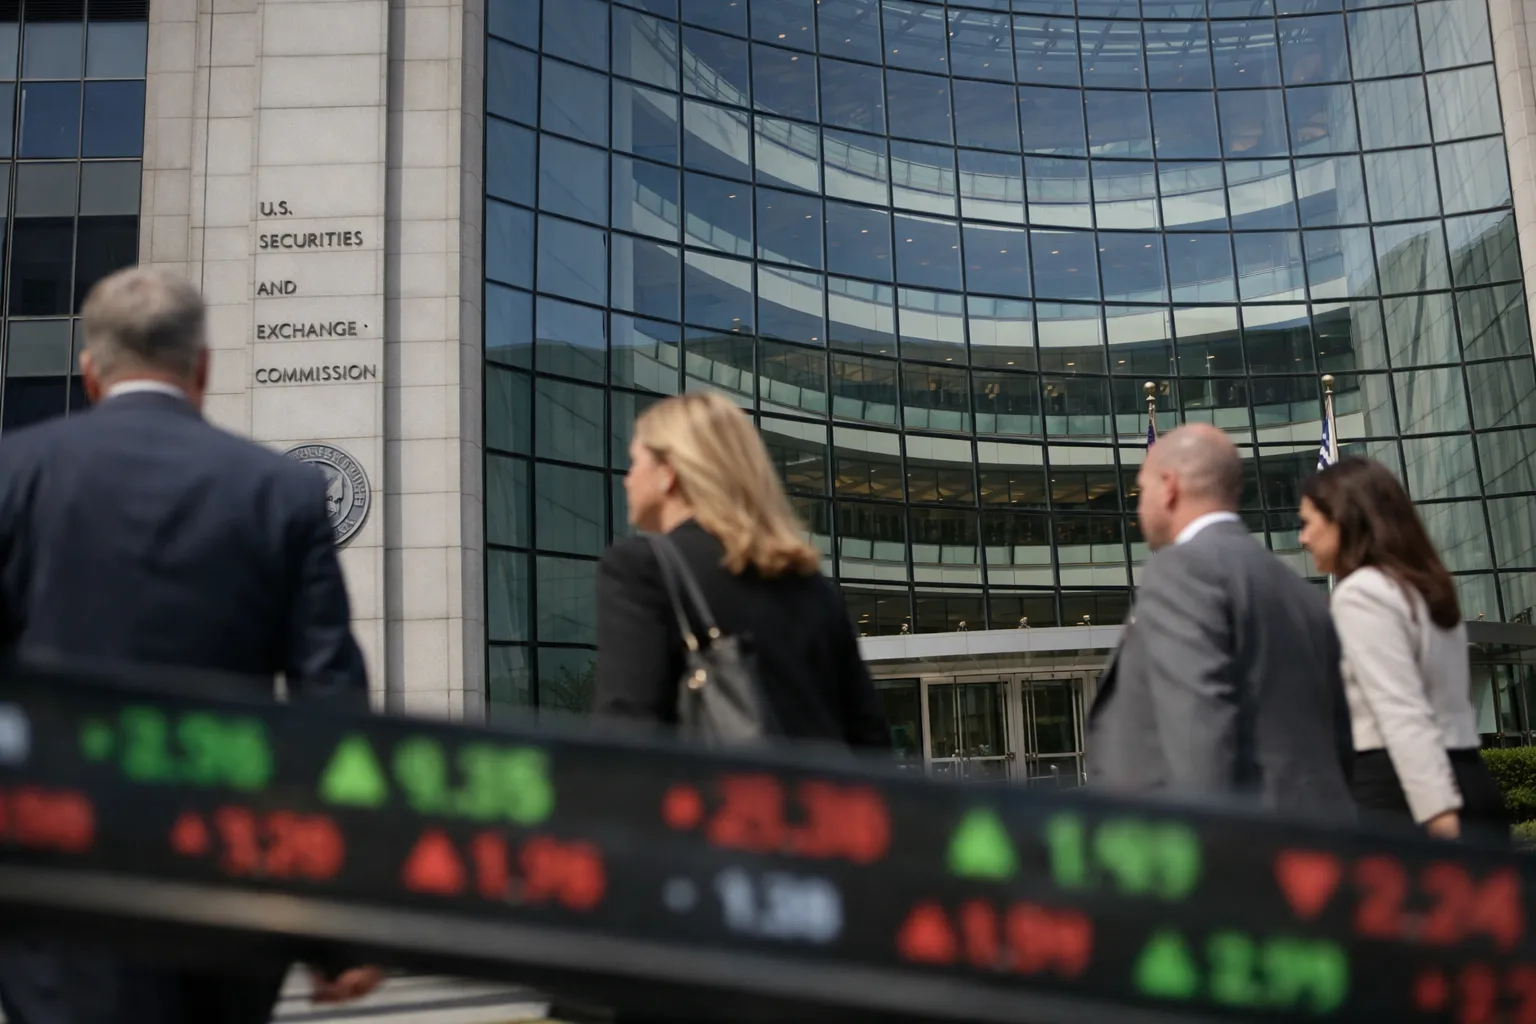
In late October 2026 the U.S. Securities and Exchange Commission unveiled a proposal that, if adopted, would require far more granular public disclosure about how retail equity orders are routed and compensated. The measure targets longstanding opacity around payment‑for‑order‑flow (PFOF), internalization and routing to dark pools and internal market‑makers—information retail investors and market participants say has been hard to assemble from scattered broker reports and quarterly filings.
What the proposal would require
The proposal, released by the commission as part of its broader market‑structure review, would oblige broker‑dealers to publish standardized retail order‑routing data on a monthly basis. Key elements include:
- Per‑venue and per‑security disclosure of routing destinations for retail orders (internalizers, market‑makers, exchanges, alternative trading systems).
- Itemized amounts paid to venues and counterparties for order flow and execution services, reported gross and net.
- Execution‑quality metrics tied to routed orders: percentage executed at NBBO, price improvement statistics and average execution latency buckets.
- A standardized public dataset format to enable third‑party analysis and back‑testing of retail execution quality over time.
The agency frames the change as a transparency upgrade intended to help investors evaluate brokers’ claims about “best execution” and to improve competition among execution venues by making performance and compensation comparable across firms.
Why this matters to investors
For stock‑market investors—even passive, long‑term retail buyers—routing and execution practices affect realized performance. Microstructure frictions such as worse‑than‑NBBO fills or persistent latency can shave basis points over time on repeated trades. The proposal matters in three practical ways:
- Verification of execution quality: Retail investors and independent analysts would be able to check whether trade confirmations and broker claims align with actual execution—how often trades receive price improvement and how often they’re internalized.
- Price discovery on PFOF economics: Making PFOF receipts public at a granular level lets investors and researchers judge whether those payments correlate with better, worse, or neutral execution outcomes.
- Competitive pressure on spreads and fees: If data show venues paying the most for order flow aren’t delivering better executions, brokers may face pressure to renegotiate or shift routing—potentially changing the economics that support commission‑free trading and subsidized retail platforms.
How brokers and market‑makers are likely to respond
Brokers that have relied on PFOF and internalization as meaningful revenue sources face several choices: maintain current routing and publish the data; change routing to favor venues that produce better public metrics; or alter their revenue model—shifting toward subscription fees, margin revenue, or optional order‑routing products.
Market‑makers and internalizers that pay for order flow may reduce payments if disclosure reveals poor return on investment, or they may invest in more measurable execution improvements—price improvement programs, speed upgrades, or explicit rebates tied to published metrics.
Expect an industry transition period. Firms will likely pilot routing changes, update trade reporting systems and lobby for phased implementation or exemptions for certain low‑latency data elements.
Potential market‑wide effects and unintended consequences
Greater transparency can produce both intended and unintended outcomes:
- Intended: Improved broker accountability, easier cross‑platform comparisons, pressure on venues to deliver genuine price improvement.
- Unintended: If PFOF revenue falls materially, some brokers may monetize otherwise free services, restrict fractional shares, or alter order types available to retail shoppers. Alternatively, venues might reduce rebates to exchanges, compressing spreads in some securities but widening them in less liquid names.
- Data‑gaming risk: Venues and brokers could optimize for published metrics at the expense of other execution dimensions not covered by the rule, a phenomenon researchers call “teaching to the test.”
What investors should do now
Retail investors and allocators should prepare to use the forthcoming data to assess execution quality. Practical steps:
- Review current trade confirmation details and broker disclosures about routing and price improvement so you have a baseline.
- When the dataset is published, compare your broker’s execution metrics with rivals over multiple months before drawing conclusions.
- Watch for product changes—subscription fees, changes to order types or fractional trading options—that brokers may announce in response to revenue pressure.
- Consider small, controlled experiments: route similar trades across platforms or use limit orders to quantify execution differences yourself.
Timeline and next steps
The SEC’s release opens a public comment period—typical for rule‑making—followed by agency review of feedback. Industry participants expect a multi‑month comment window and a realistic implementation horizon extending into 2027 if the rule advances. Market participants and trade groups will likely press for narrow carve‑outs (for latency‑sensitive data) and for phased compliance deadlines to allow technology upgrades.
For investors, the proposal signals the next stage of market‑structure reform: regulators are shifting from broad principles to machine‑readable detail. If adopted, the rule will give retail investors and independent researchers a tool to hold brokers and venues accountable for execution outcomes—an incremental but meaningful step in a market where information asymmetries have long shaped how orders are routed and filled.