
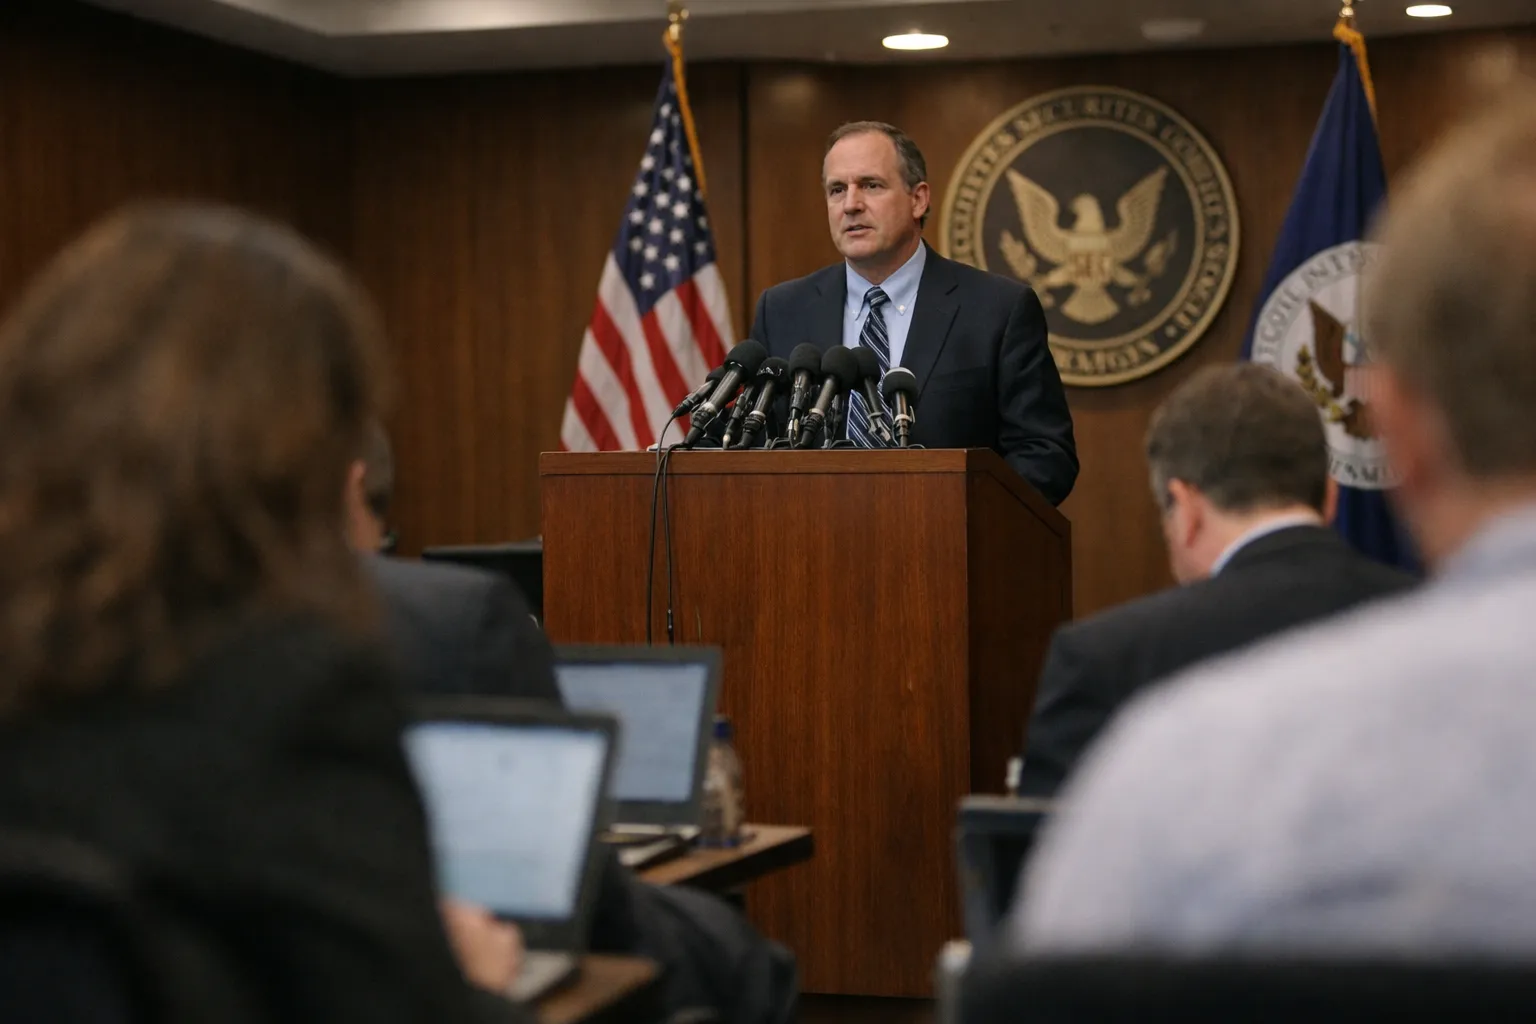
WASHINGTON, D.C., July 8, 2026 — The U.S. Securities and Exchange Commission’s proposal to require some actively managed exchange‑traded funds that rely on proxy portfolios to publish intraday holdings as frequently as every 15 minutes is still moving through the rulemaking pipeline. Since the May 24, 2026 comment deadline, regulators, major ETF sponsors and market‑data firms have produced new pilots, templates and operational proposals that sharpen the trade‑offs at stake: narrower displayed spreads versus higher in‑fund execution costs for certain active strategies.
Context: why this still matters
ETFs remain core market plumbing: U.S.-listed ETFs held roughly $9 trillion at end‑2025, and active ETFs represent about 10%–15% of that pool depending on classification. The SEC’s March 25, 2026 proposed rule targeted active ETFs that use proxy portfolios for creations and redemptions and set a default disclosure cadence of every 15 minutes during market hours, with carveouts for extremely illiquid holdings.
The numbers tell a different story than marketing slogans like “more transparency, better outcomes.” Early and expanded pilot data show that disclosure can compress displayed spreads by a few basis points for liquid products, while raising managers’ realized execution costs by several basis points for illiquid or high‑turnover funds. Where those basis points land—inside the fund or in the bid‑ask—determines whether retail buy‑and‑hold investors or active traders net a benefit.
What changed since late May 2026
- SEC staff roundtable and technical guidance (June 18, 2026). The SEC convened a public roundtable to review empirical evidence and operational readiness. Staff emphasized they are considering hybrid approaches that would preserve a 15‑minute default while allowing conditional redactions, short “blackout” windows for highly illiquid positions, or publication of intraday risk metrics instead of full line‑by‑line holdings in certain cases.
- Expanded pilot results. Two independent analytics firms—MarketLens Analytics and AlphaMetrics—published an expanded pilot on June 30, 2026 covering 350 active ETFs over a three‑month test. Key findings: median intraday quoted spreads narrowed by 3–7 basis points for the 220 largest‑liquidity funds; for 130 smaller or concentrated funds, managers reported median increases in realized in‑fund execution cost of 6–10 basis points. Turnover‑heavy funds (annualized turnover above 40%) showed the largest internal cost increases.
- Exchange and industry templates. On July 1, 2026, NYSE and Nasdaq released standardized technical templates for proxy‑portfolio feeds—file formats, latency targets and authentication standards—intended to reduce integration costs for issuers and APs. The templates include schema for redaction flags and a “liquidity score” metadata field for each holding.
- Issuer positions firm up. Major sponsors—BlackRock, Fidelity, Invesco—and the Investment Company Institute (ICI) reiterated public concerns in June filings and meetings: support for investor information, but requests for narrow exceptions (e.g., temporary redactions for less than 10% of NAV) and for measurement studies that separate displayed spread improvements from manager execution cost increases.
Details: which funds change and how
The practical effect depends on liquidity profile and turnover. For large‑cap, diversified active ETFs with average daily dollar volume (ADTV) above $100 million and turnover under 25% annualized, expect displayed spreads to tighten by roughly 2–6 bps in normal conditions — a small but meaningful saving for frequent traders. For concentrated small‑cap, frontier‑market, thematic or sector funds with ADTV under $10 million and turnover above 40%, the expanded pilot shows a median realized execution‑cost increase of 6–10 bps after disclosure—effectively moving costs from the bid‑ask to the fund’s performance line.
Concrete example from the June pilot: a 30‑name small‑cap active ETF with pre‑disclosure midday quoted spread of 40 bps saw that spread fall to 33 bps (7 bps improvement). However, the manager’s post‑trade reports showed average slippage on internal hedging trades increased by 9 bps, meaning long‑term holders experienced a net drag on returns despite tighter displayed spreads.
Impact: what individual investors should watch now
If you own active ETFs, your relevant outcome still depends on horizon and trading behavior. Here’s what to measure and why:
- Median bid‑ask spread (bps): look at monthly figures; a 3–7 bps reduction helps high‑frequency traders but may be offset by internal costs for long‑term holders.
- Trailing 12‑month tracking difference (%):
- Reported annualized turnover (%):
- Manager disclosure policy:
Updated, practical steps for July 2026:
- Record three numbers monthly for each active ETF: median bid‑ask spread (bps), trailing 12‑month tracking difference (%), and reported annualized turnover (%).
- Use limit orders by default, especially at open/close. For illiquid active ETFs, prefer limit orders placed off the midpoint; open and close remain the riskiest times.
- Favor funds that disclose creation/redemption mechanics (in‑kind vs. cash) and publish an iNAV or intra‑day risk indicators; these practices mitigate tax and execution surprises.
- Monitor fund prospectus updates and sponsor comment letters—issuers proposing hybrid solutions (e.g., 15‑minute proxy feeds plus temporary redactions) may preserve investor transparency while protecting managers’ execution quality.
Reactions and who’s talking
Industry split remains. Asset managers and the ICI pushed for calibrated exceptions and operational standards; exchanges emphasized technical feasibility and released templates to lower implementation costs. Market‑structure researchers and some investor advocates point to the pilot evidence of narrower spreads as a retail benefit, while independent analytics firms highlight the net impact varies by liquidity and turnover. Several trading analytics vendors proposed a hybrid model—regular proxy disclosure with a limited “redaction cap” (for example, up to 10% of NAV or positions below a liquidity threshold) and mandatory reporting of redaction events.
“The right result will balance intraday price discovery against the risk of turning active management into a mechanical execution problem,” one market‑structure researcher told analysts in late June. The numbers from expanded pilots suggest that balance is achievable but nuanced.
What’s next — timeline to watch
- Q3–Q4 2026: SEC staff expected to synthesize comments and pilot data into a revised proposal or next‑step guidance. Industry sources say a modified proposal that formalizes hybrid options (redaction windows, liquidity flags, or alternative risk metrics) is increasingly likely.
- Implementation window: any final rule would likely include an 18–24 month phase‑in to allow issuers, exchanges and APs to implement feeds and new operational safeguards.
- Watch:
Bottom line
The policy trade‑off is unchanged: more frequent intraday disclosure tends to shift costs, not uniformly reduce them. If you trade actively, expect some benefit from tighter displayed spreads. If you hold active ETFs for the long run, be vigilant: the fine print—turnover, creation mechanics, redaction policies—will determine whether costs show up in your returns. The numbers tell a different story for different funds; measure spreads, tracking difference and turnover monthly and prefer managers with transparent creation practices and an intra‑day NAV or risk metric.
FAQ
Will the 15‑minute rule apply to index ETFs like SPY or VTI?
Unlikely. The SEC’s March 25 proposal and subsequent staff comments target actively managed ETFs that rely on proxy portfolios for creations/redemptions. Index ETFs that follow published indices (e.g., SPY, VTI) already provide rules‑based holdings and aren’t the main focus.
Does intraday disclosure always reduce costs for retail investors?
No. Expanded pilots in June 2026 show mid‑day quoted spreads narrowing by about 3–7 bps for many funds, but managers of illiquid or high‑turnover funds reported increases in realized in‑fund execution cost of roughly 6–10 bps. Net effect depends on your trade frequency and the fund’s liquidity and turnover profile.
How can I tell if my active ETF will be affected?
Check whether the fund uses a proxy portfolio for creations/redemptions, its average daily dollar volume (ADTV), and its annualized turnover. Funds with ADTV under ~$10 million or turnover above ~30% are the most likely to see meaningful effects.
What should taxable investors monitor?
Watch reported realized turnover and any unplanned short‑term capital gains disclosed in monthly or annual reports. Increased arbitrage activity can raise in‑fund trades and potentially trigger taxable events for shareholders.
What practical monitoring routine should I use now?
Monthly, record: (1) median bid‑ask spread (bps), (2) trailing 12‑month tracking difference (%), and (3) reported annualized turnover (%). If spreads improve but tracking difference or turnover worsens, the fund’s cost profile has shifted rather than improved.